Blog Content
Are You Overpaying for Auto Insurance Rates Right Now?
Auto insurance rates in 2026 are putting real pressure on household budgets — but most drivers have no idea how much they're overpaying.
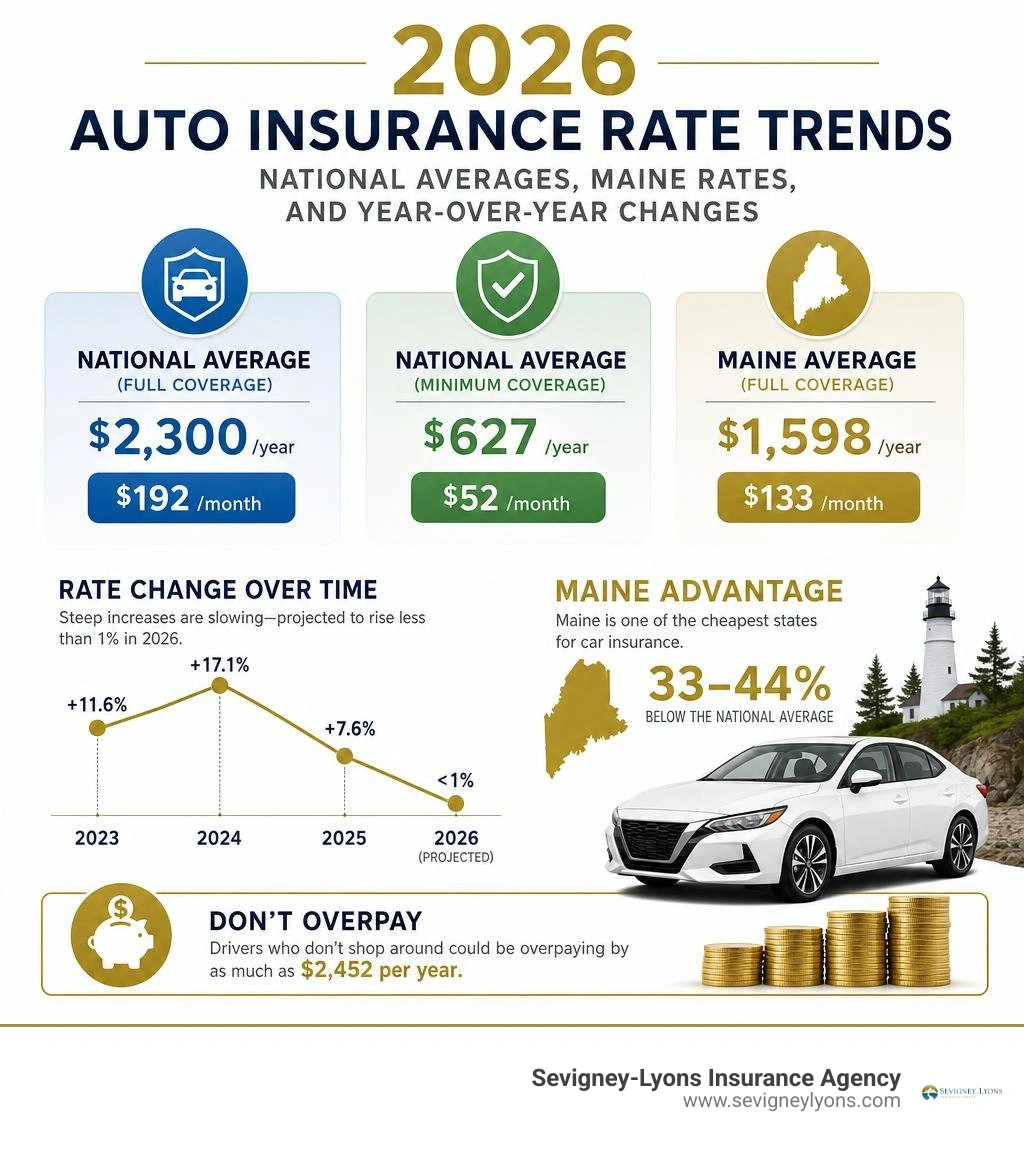
Here's a quick snapshot of where rates stand today:
The good news? After three years of steep increases — 11.6% in 2023, 17.1% in 2024, and 7.6% in 2025 — rate growth is finally slowing. Prices are projected to rise less than 1% in 2026, the smallest increase since 2022.
The bad news? Drivers who don't shop around could still be overpaying by as much as $2,452 per year. That's money left on the table — every single year.
For drivers in Southern Maine — whether you're in Wells, Kennebunk, Ogunquit, or Biddeford — there's actually a real advantage. Maine is one of the cheapest states in the country for car insurance, averaging 33–44% below the national average. But even here, the difference between the cheapest and most expensive insurer can be dramatic.
I'm Jon Sevigney, and in this guide I'll walk you through exactly what's driving your premium, how Maine stacks up, and the practical steps you can take to stop overpaying today.
Basic auto insurance rates vocab:
Understanding National Auto Insurance Rates in 2026
To understand why your bills look the way they do, we have to look at the broader national landscape. The insurance industry is currently entering what economists call a "stabilization phase." After years of aggressive hikes, insurance carriers are finally reaching "rate adequacy"—meaning the premiums they collect are finally aligned with the actual cost of paying out claims.
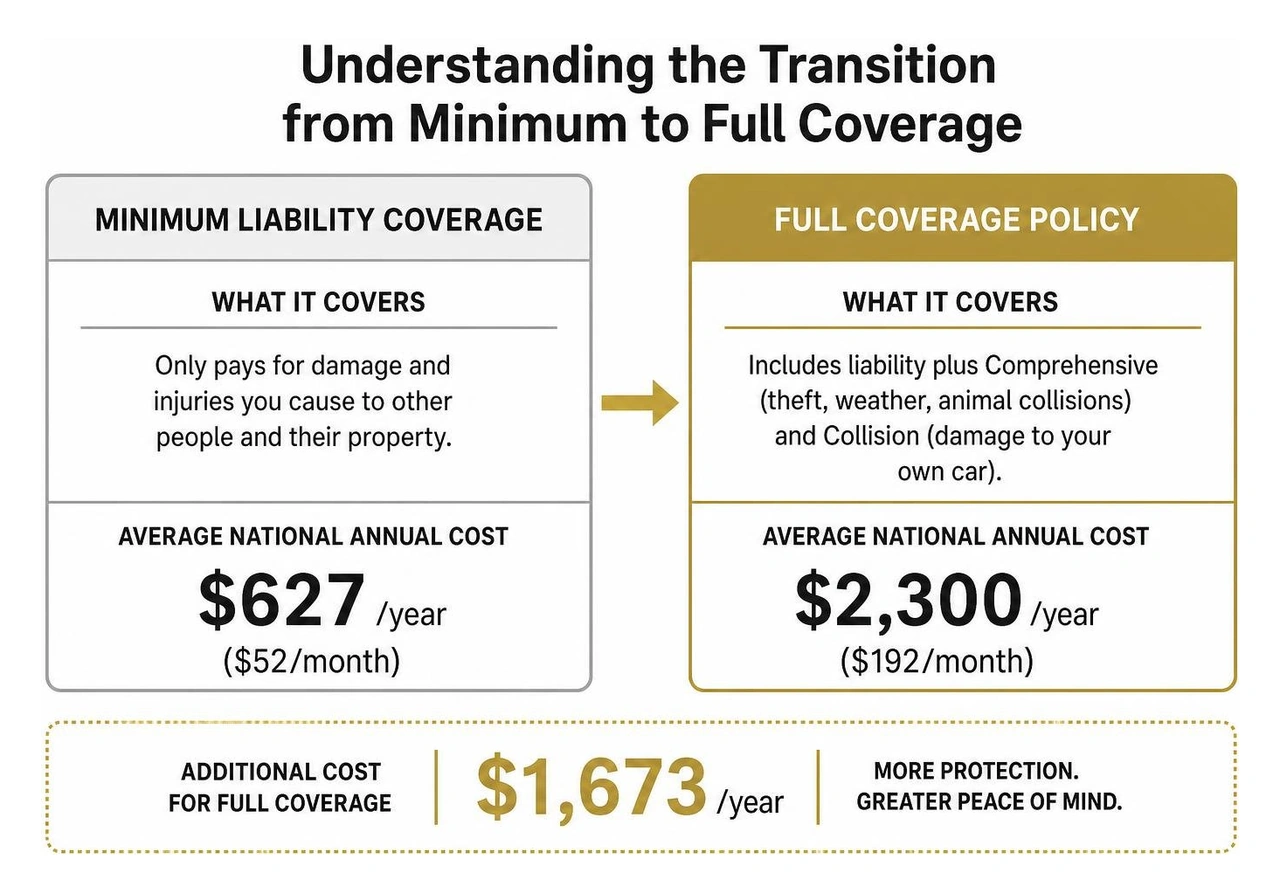
According to recent industry data, the national average cost of car insurance is $2,273 annually (about $189 per month) when blending all coverage levels, while full coverage averages $2,924 globally across all profiles, and minimum coverage sits at $1,572. However, when looking at standard driver benchmarks, the baseline average for full coverage is roughly $2,300 per year, compared to just $627 for minimum liability.
This stabilization is a welcome relief. Between 2023 and late 2025, carriers faced a perfect storm: high inflation, a massive spike in the cost of high-tech vehicle parts, and severe weather events. While overall auto insurance rates are expected to increase by an average of less than 1% in 2026, the legacy of those previous hikes remains.
To see how these coverage options stack up, let's look at how policy choices change your baseline costs:
If you want to make sure you aren't stuck with an inflated premium, you have to actively Compare Auto Insurance Rates. Relying on the same company year after year without checking the broader market is the easiest way to overpay.
Regional Disparities: How Maine Compares to the Rest of the Country
Location is one of the most powerful factors in determining your auto insurance premiums. If you live in Southern Maine—whether you are commuting along Route 1 in Wells, parking near the beach in Ogunquit, navigating the downtown rotary in Kennebunk, or driving to work in Biddeford—you are in a highly favorable position.
According to recent industry rate analyses, the cost gap between the most expensive and cheapest states has widened to a staggering 2.5x. On one end of the spectrum, drivers in states like Louisiana and Florida face staggering average annual premiums of over $3,200 due to high litigation rates, severe weather risks, and dense traffic.
On the other end, Maine consistently ranks as the second-cheapest state in the entire country for auto insurance. Our average full coverage premium of $1,354 to $1,598 per year is roughly 33% to 44% below the national average.
Several factors drive Maine's incredibly low rates:
- Lower Population Density: Fewer cars on the road mean fewer multi-car accidents.
- Fewer Uninsured Drivers: Maine has strict compliance laws, meaning responsible drivers don't have to absorb the costs of uninsured motorists to the same degree as other states.
- Local Risk Profiles: While we do deal with harsh winter weather, our overall litigation environment is much more stable than states like Florida or Louisiana.
However, "cheap" is relative. If you live in Ogunquit, local rates can still vary by hundreds of dollars depending on the carrier you choose. That is why having a localized guide like our Cheap Auto Insurance Maine Guide 2026 is so critical. We help you navigate the specific local carriers that offer the best rates for Southern Maine's unique geography.
Key Factors That Drive Your Personal Premium Costs
While state averages give us a great baseline, insurance companies don't price policies based on averages. They price them based on your specific risk profile.
Underwriters look at dozens of personal factors to estimate the statistical probability that you will file a claim. If you understand how these factors are weighed, you can take active steps to manage them.
How Age and Gender Impact Auto Insurance Rates
It is no secret that young drivers pay the highest rates in the industry. Because of a statistical lack of experience behind the wheel, teenagers and drivers in their early twenties are far more likely to be involved in accidents.
According to national data, the average cost of car insurance for a 20-year-old driver is a staggering $4,687 per year for full coverage. There is also a notable gender gap at younger ages: a 20-year-old male driver can pay up to $826 more per year than a female driver of the exact same age. However, this gender gap almost entirely evaporates by age 35, shrinking to an average difference of just $28 per year.
For local families, navigating these years can be incredibly stressful. We highly recommend checking out our resources on Maine Auto Insurance for Young Drivers and reviewing our tips on finding the Best Cheapest Car Insurance Young Driver to keep those youthful premiums from breaking your family budget.
The Role of Driving Records and Credit Scores on Auto Insurance Rates
Your driving record is the single most direct reflection of your risk on the road. In 2026, a single ticket or at-fault accident can raise your auto insurance rates by an average of 54%.
Let's look at how much a single mistake can cost you annually on a full coverage policy:
- Clean Record: ~$2,118/year
- Speeding Ticket: ~$2,947/year (a 28% increase)
- At-Fault Accident: ~$3,435/year (a 49% increase)
- DUI Conviction: ~$4,342/year (an 89% increase)
In Maine, these infractions are governed by specific state guidelines. Understanding the Maine Car Insurance Laws 2025 can help you understand how long points stay on your license and how they affect your premium over time.
Additionally, your credit score plays a massive role in what you pay. In states where it is legally permitted—including Maine—insurers use credit-based insurance scores to determine rates. On average, full coverage premiums are about 70% higher for drivers with poor credit ($3,911/year) than for those with good credit ($2,300/year). Keeping your credit score above 700 is one of the most effective ways to keep your insurance costs low.
Policy Types and Vehicle Choices: Balancing Protection and Cost
Beyond your personal background, the specific policy you build and the vehicle you park in your driveway will directly dictate your monthly premium.
Full Coverage vs. Minimum Liability in Maine
In Maine, you are legally required to carry a minimum amount of liability insurance to cover bodily injury and property damage if you cause an accident. While choosing the bare minimum is always the cheapest option upfront, it leaves you completely unprotected if your own vehicle is damaged, stolen, or totaled.
A comprehensive policy protects you from local risks like hitting a deer on Route 9 or dealing with falling ice during a coastal nor'easter. To understand the exact differences in what these policies protect, read our Full Coverage Automobile Insurance Guide and explore our localized breakdown of Full Coverage Auto Insurance Maine to find the right balance of protection and value.
How Your Vehicle Type Affects Your Premium
The vehicle you drive has a massive impact on your premium. Modern cars are packed with advanced safety features, but those same features make them incredibly expensive to repair. A simple bumper scrape that used to cost $500 to fix can now cost $3,000 because of the advanced sensors and cameras embedded inside.
This issue is particularly pronounced with electric vehicles (EVs). On average, EVs cost $309 per month to insure, which is 18% more than gas-powered cars. However, there is a major distinction between manufacturers:
- Legacy Manufacturers (Chevrolet, Ford, Honda): EVs from these brands cost about 49% less to insure than startup EV brands because they use established, highly accessible replacement parts.
- EV-Only Brands (Tesla, Rivian): These vehicles require specialized repair networks and proprietary parts, which drives up loss severity and premium costs.
Before you purchase your next vehicle, it is incredibly smart to check out Maine Comprehensive Car Insurance Rates to see how your prospective car will affect your monthly bills.
Actionable Strategies to Lower Your Premiums
You don't have to sit back and accept rising insurance bills. There are several highly effective, practical strategies you can use to lower your rates today:
- Bundle Your Policies: Bundling your home and auto insurance with the same carrier is the single most effective discount available, saving drivers between 11% and 24% on average.
- Raise Your Deductible: Moving your collision and comprehensive deductible from $250 to $500 or $1,000 can lower your premium significantly. Just make sure you keep enough cash in emergency savings to cover that deductible if you ever need to file a claim.
- Inquire About Niche Discounts: Ask about paperless billing, pay-in-full discounts, low-mileage discounts, or safe driving courses that can save you an easy 10% for multiple years.
- Schedule a Professional Policy Review: Your life changes, and your insurance should change with it. Scheduling an Auto Insurance Policy Review Maine with a local agent is the best way to uncover hidden savings and ensure you have the Best Auto Insurance Coverage in Maine.
Frequently Asked Questions About Maine Car Insurance
Why are my auto insurance rates so high in Southern Maine?
Even though Maine is highly affordable compared to the rest of the nation, local rates in Wells, Kennebunk, Ogunquit, and Biddeford can still feel high. This is typically driven by localized winter driving hazards, rising vehicle repair inflation, and comprehensive claims related to wildlife collisions (such as deer or moose).
How much can I save by shopping around for car insurance?
A lot. National data shows that drivers can overpay by as much as $2,452 per year by staying with the wrong carrier. For example, the difference between the most expensive carrier and the cheapest carrier for the exact same driver profile in Kennebunk can represent hundreds of dollars in annual savings.
Does Maine allow credit scores to affect auto insurance pricing?
Yes. Unlike states like California and Massachusetts, Maine legally allows insurance companies to use credit-based insurance scores to help determine auto premiums. Maintaining a strong credit history is one of the most reliable ways to secure the lowest possible rates in our state.
Conclusion
Finding the best auto insurance rates doesn't mean you have to spend hours typing your personal information into random online comparison sites that sell your data to telemarketers.
At Sevigney-Lyons Insurance Agency, we do the heavy lifting for you. As an independent insurance agency deeply rooted in Southern Maine, we have access to over 20 of the nation's top insurance carriers. This means we don't just sell you a one-size-fits-all policy—we shop the entire market to find the absolute best rates and coverage tailored specifically to your family or business.
Whether you want to drop by our Wells office for a face-to-face chat or handle everything from the comfort of your home, we are here to help you stop the financial bleeding and secure the peace of mind you deserve.
Ready to see how much you could save? Get a Free Maine Auto Insurance Quote from our local team today!