Blog Content
Find Local Home Insurance Help That Fits Your Maine Home
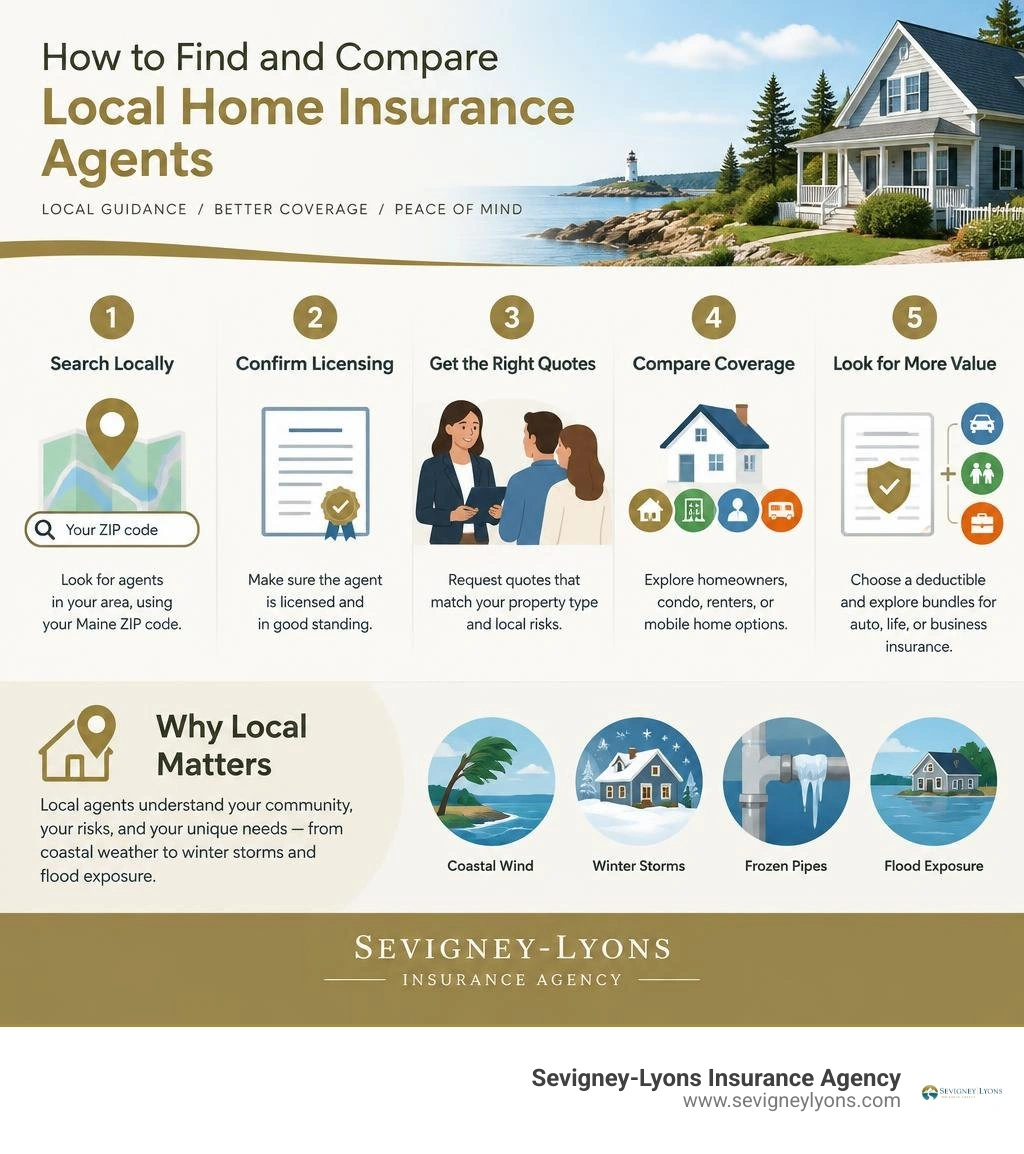
To find home insurance agents near me, search by your Maine ZIP code, confirm the agent is licensed, and ask for quotes that match your property type and local risks. A good local agent can help you compare homeowners, condo, renters, or mobile home coverage, choose a deductible, and explore bundles for auto, life, or business insurance.
For homeowners in Wells, Kennebunk, Ogunquit, and Biddeford, local knowledge matters. Coastal wind, winter storms, frozen pipes, and flood exposure can all affect the protection your home may need. An agent can also explain what a standard policy covers, what it excludes, and whether added coverage is worth considering.
I am Jon Sevigney, and this guide will help you find and evaluate a local agent who can make home insurance clearer and more personal.
Why Choosing Maine Home Insurance Agents Near Me Matters
Buying a home or safeguarding an existing property is one of the most significant financial investments you will ever make. While generic websites offer automated pricing algorithms, insurance is not a one-size-fits-all commodity. When you search for local insurance assistance, working with nearby professionals ensures you receive guidance tailored to your specific community rather than a standardized template generated hundreds of miles away.
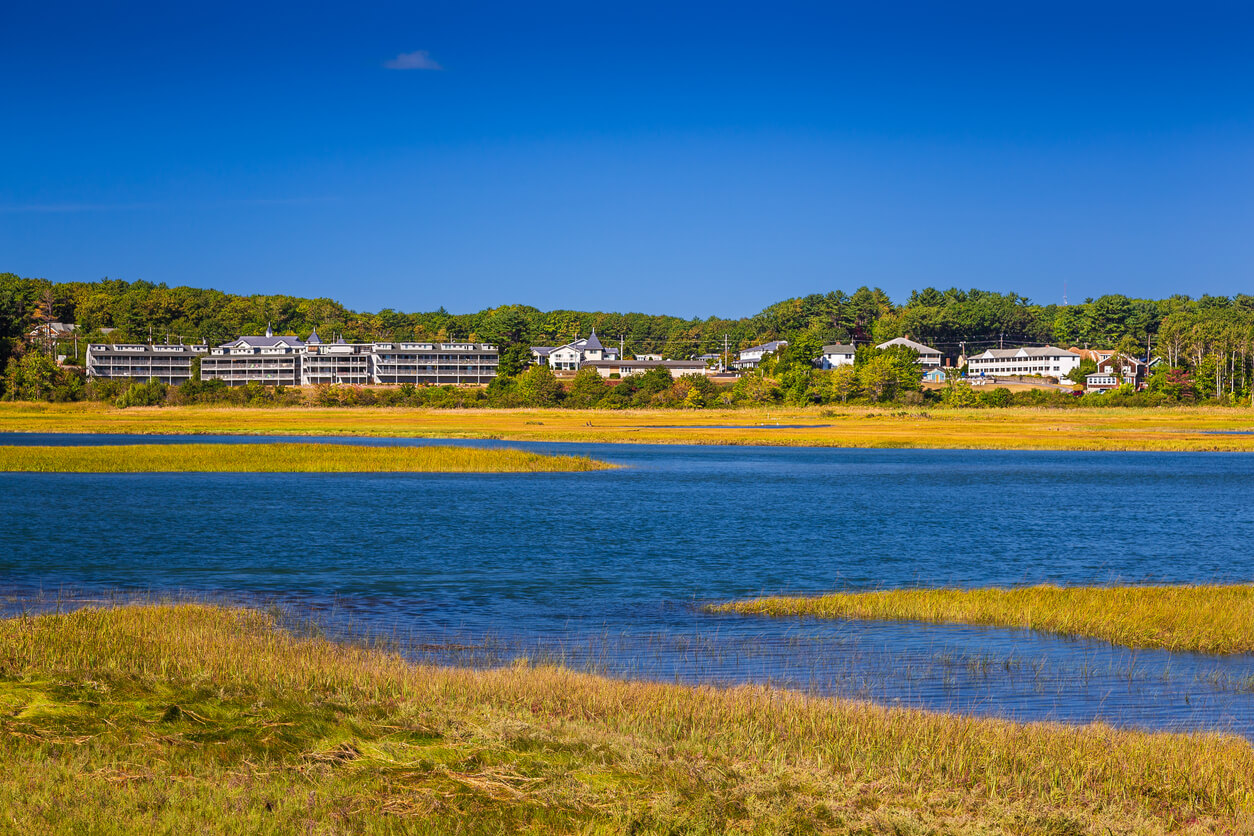
Southern Maine presents unique environmental considerations that direct online call centers often miss. From Nor'easters sweeping through coastal neighborhoods to sub-zero temperatures causing burst pipes, your property faces distinctive regional perils. When navigating these situations, partnering with the best local insurance in Maine gives you access to a dedicated advocate who understands our local weather patterns, municipal building codes, and municipal emergency resources.
Local agents act as your personal claims advocate. If a heavy blizzard or coastal storm causes structural damage, having someone in your corner who lives and works in the same community simplifies the recovery process. We walk you through every step, answer your calls directly, and help you document damage accurately, eliminating the stress of dealing with endless automated phone queues.
Local Risk Expertise in Southern Maine
Every town in Southern Maine features distinct geographical and environmental risks:
- Wells & Ogunquit: Homes situated near coastal marshes or oceanfront roads face higher exposure to storm surges, saltwater corrosion, and high-velocity coastal winds.
- Kennebunk & Biddeford: Historic properties and inland residences often deal with mature tree fall risks, freezing temperatures that threaten older plumbing, and specific municipal zoning guidelines.
Understanding these differences requires localized experience. Our experienced Maine insurance advisors analyze localized flood maps, municipal building requirements, and winter weather exposure to ensure your dwelling coverage limits reflect true local rebuilding costs rather than broad national estimates.
How Home Insurance Agents Near Me Simplify Relocations
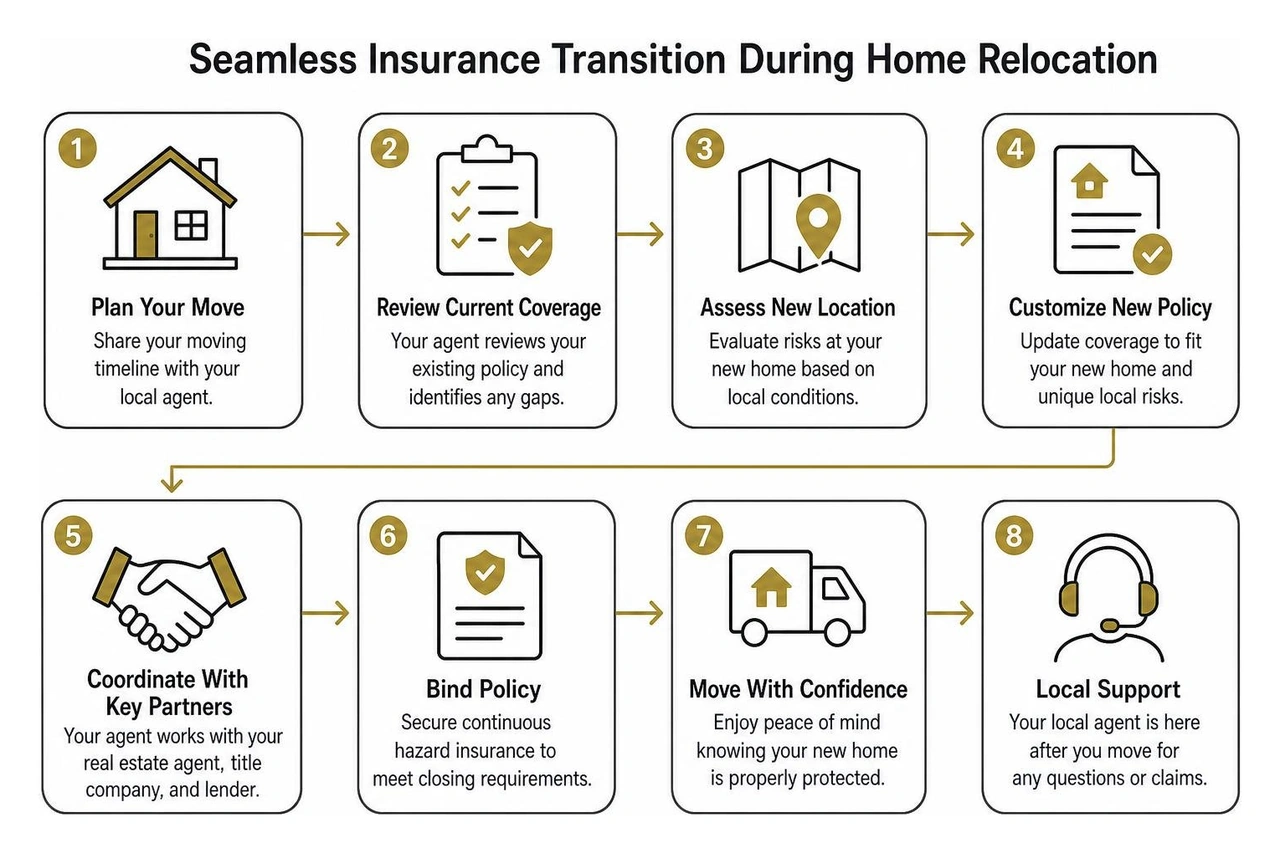
Relocating across state lines or moving between towns in Maine involves dozens of moving parts. Local insurance agents streamline this transition by coordinating directly with your real estate agent, title company, and mortgage lender.
When you purchase a property in Southern Maine, lenders require proof of continuous hazard insurance before closing day. A nearby agent understands local underwriting requirements, ensuring your policy is bound promptly to prevent closing delays. If you are moving from out of state, an advisor will review your previous coverage, identify gaps related to winter weather or coastal risks, and set up your new policy smoothly.
5 Key Factors to Evaluate When Finding an Agent
Selecting the right professional to protect your property requires evaluating more than just the lowest initial premium. Use these essential criteria to choose a reliable partner:
- Independent vs. Captive Representation: Independent agencies represent multiple insurance carriers, shopping the market on your behalf to find the best balance of coverage and cost. Captive agents only offer products from a single company.
- Proper Licensing & Regulatory Standing: Ensure the agent and agency maintain active, good-standing licenses with state regulatory boards. You can learn more about how insurance regulation works through the National Association of Insurance Commissioners.
- Local Community Reputation: Review client feedback, community involvement, and local tenure. Long-standing local ties reflect reliable service and stability.
- Comprehensive Product Offerings: A full-service agency can manage your home, vehicle, umbrella, and business coverage under one roof, unlocking valuable multi-policy discounts.
- Direct Accessibility: Look for advisors who provide multiple ways to communicate, including in-person office visits, direct phone lines, email, and virtual consultations.
For a deeper dive into evaluating your coverage options, review our guide to finding the best home insurance in Maine.
Multi-Carrier Access and Policy Bundling
Working with an independent insurance agency gives you access to a wide network of regional and national insurance carriers. Instead of being locked into a single pricing structure, your advisor can compare rates, coverage forms, and endorsement options across top-rated carriers.
Bundling your property coverage with auto, recreational vehicle, or umbrella liability policies is one of the most effective strategies to lower your total annual premium. Exploring comprehensive personal insurance coverage in Wells, Maine allows you to streamline all your policies with a single advisor, simplifying renewals and claims while maximizing multi-policy credits.
Verifying State Licensing and Credentials
Before sharing sensitive personal information or purchasing a policy, always verify that the agent and agency are fully licensed. State regulatory bodies govern insurance operations to ensure ethical practices, financial stability, and consumer protection.
In Maine, the state government maintains an accessible database through the Maine Bureau of Insurance. You can quickly search for an individual producer or agency name to confirm active licensing status, lines of authority (such as Property & Casualty), and compliance history. Reputable agencies proudly display their licensing credentials and are happy to provide their producer numbers upon request.
Types of Coverage Offered by Local Property Agents
A standard property policy is built from several core coverage components designed to protect your physical structures and financial wellbeing:
- Dwelling Coverage (Coverage A): Pays to repair or rebuild the physical structure of your home if damaged by covered perils such as fire, wind, hail, or lightning.
- Other Structures (Coverage B): Protects detached buildings on your land, including garages, sheds, gazebos, and fences.
- Personal Property (Coverage C): Reimburses you for personal belongings—such as furniture, electronics, and clothing—damaged or destroyed by a covered loss.
- Loss of Use / Additional Living Expenses (Coverage D): Covers temporary housing, hotel bills, and restaurant meals if your home becomes uninhabitable during covered repairs.
- Personal Liability (Coverage E): Protects your financial assets if someone is injured on your property or you accidentally cause property damage to others.
- Medical Payments (Coverage F): Pays minor medical expenses for guests injured on your property, regardless of fault.
Understanding these foundational protections ensures you choose the best homeowners insurance coverage in Maine for your family.
Homeowners, Condo, and Mobile Home Coverage
Different types of residential properties require distinct policy structures:
- Single-Family Homeowners (HO-3 / HO-5): Comprehensive policies covering the dwelling, other structures, personal belongings, and personal liability.
- Condominium Insurance (HO-6): Designed for condo unit owners. It works in tandem with your condo association's master policy, covering your interior walls, fixtures, improvements, personal property, and liability.
- Mobile & Manufactured Home Coverage: Specialized protection tailored to the unique structural and anchoring characteristics of manufactured homes.
Homeowners vs Renters Insurance Protection
If you rent an apartment or house, your landlord's insurance only covers the physical building—it does not protect your personal belongings or shield you from personal liability claims. Renters insurance (HO-4) fills this critical gap at an affordable price point.
The following table highlights the key operational differences between homeowners and renters insurance:
What You Need to Prepare for Your Insurance Quote
Gathering standard property details in advance makes the quoting process fast and precise. When your local agent has accurate data, they can identify eligible discounts and structure coverage that eliminates potential underinsurance risks.
Essential Property Details and Home History
To generate an accurate property insurance quote, have the following details ready:
- Property Basics: Square footage, year built, number of stories, and foundation style.
- Roof Information: Approximate age of the roof, style (gable, hip, flat), and materials (asphalt shingle, metal, slate).
- Heating & Plumbing Systems: Primary and secondary heating sources (oil, propane, heat pumps, wood stoves), electrical panel type (circuit breakers vs. fuses), and plumbing materials.
- Safety & Mitigation Devices: Smoke detectors, hardwired fire alarms, carbon monoxide detectors, deadbolts, and security systems.
- Renovations & Upgrades: Dates of major improvements, such as kitchen remodels, electrical rewiring, or plumbing replacements.
- Prior Claims History: Details regarding any property insurance claims filed within the past 3 to 5 years.
Connecting with Home Insurance Agents Near Me for Personalized Rates
Once you have gathered your property details, your agent will calculate the estimated replacement cost of your home. This figure represents the actual labor and material costs required to rebuild your home from the foundation up, which is distinct from the real estate market value or municipal tax assessment.
Your advisor will guide you through crucial policy selections, such as:
- Choosing Your Deductible: Selecting a higher deductible (e.g., $1,000 or $2,500) reduces your annual premium, while a lower deductible reduces out-of-pocket expenses when a claim occurs.
- Valuable Endorsements: Adding endorsements such as water backup of sewers/drains, service line coverage, equipment breakdown, or scheduled personal property for high-value jewelry and art.
Frequently Asked Questions About Local Insurance Agents
What is the difference between homeowners insurance and renters insurance?
The primary difference lies in structural ownership. Homeowners insurance covers both the physical structure of the dwelling and the personal property inside it. Renters insurance does not cover the building structure—which remains the landlord’s responsibility—focusing instead on protecting the tenant's personal belongings, temporary living expenses, and personal liability.
How do I verify if an insurance agent is licensed in Maine?
You can verify an agent’s license by visiting the official Maine Bureau of Insurance website. Use their online licensee search tool to enter the producer’s name or agency name. The portal will display active license statuses, lines of authority, expiration dates, and any formal regulatory actions.
Can local agents assist non-English speakers or provide accessibility accommodations?
Yes. Professional insurance agencies prioritize accessibility by offering services across multiple channels. Many agencies provide multilingual staff or translation support for non-English speakers, American Sign Language (ASL) accommodations, wheelchair-accessible office locations, and remote consultation options via phone or secure video conferencing.
Conclusion
Protecting your home requires dependable coverage designed by professionals who understand your local environment. Rather than relying on generic internet quote tools, working with experienced local advisors provides personalized coverage, multi-carrier pricing options, and dedicated claims support right in your community.
At Sevigney-Lyons Insurance Agency, we combine decades of insurance expertise with deep roots across Southern Maine. Whether you are buying your first home in Kennebunk, updating your coastal property coverage in Wells or Ogunquit, or managing a household in Biddeford, our team is here to help. Request a free Maine insurance coverage quote today to secure reliable protection and peace of mind for your home.